
Andorran banks: how they work, advantages, and how to open an account
The Andorran banking system often attracts the attention of people considering moving to the Principality, as well as those wishing to set up a business there or simply manage part of their wealth in the country. Its historical reputation for discretion remains in the public mind, even though this no longer really reflects how the sector operates today.
Nowadays, opening and using a bank account in Andorra involves identity checks, proof of the origin of funds, and, for international clients, particular attention to tax residency. Andorra also participates in international mechanisms for the automatic exchange of financial information. In 2025, the country further strengthened its cooperation with the European Union to adapt these exchanges to updated OECD standards.
An Andorran bank can nevertheless be of real interest to a resident, entrepreneur, or investor with international needs. However, it is important to understand what the country's banks actually offer, their access requirements, and the regulatory constraints involved in opening an account.
The different banks in Andorra
The Andorran banking landscape has become significantly more concentrated in recent years. The country's banking system now consists of three groups: Andbank, MoraBanc, and Creand. Andorran Banking, the sector's professional association, confirms that these three institutions currently make up the Andorran banking system.
This clarification is important because some information still available online mentions Vall Banc or Banc Sabadell d'Andorra as independent institutions. This information reflects an earlier configuration of the market and no longer corresponds to the current situation.
Andbank has historically had a strong presence in private banking and wealth management. MoraBanc operates in commercial banking, private banking, and asset management. Creand, formerly known under the Crèdit Andorrà brand, is also one of the three major groups currently shaping the market.
Despite the country's small size, the financial weight of these institutions is far from insignificant. According to data published by Andorran Banking for the 2025 financial year, the three groups had approximately €21.76 billion in assets and more than €113 billion in assets under management. The sector also reported an aggregated regulatory CET1 ratio of 17.16% at the end of 2025.
These figures help illustrate the particular nature of the Andorran model: banks do not only serve the needs of the local population. A significant part of their business involves private banking, asset management, and supporting clients with financial interests in several countries.
What services do Andorran banks offer?
For a resident, the day-to-day operation of an Andorran bank is broadly similar to that of a bank in France or Spain. Customers can have a current account, payment cards, make transfers, set up direct debits for certain payments, and use online banking services.
The differences become more apparent when needs are more complex. The country's main banks are particularly active in private banking, asset management, and wealth management services. Andorran Banking identifies commercial banking, private banking, and asset management among the main activities of institutions in the sector.
For an entrepreneur based in Andorra, banking needs may include managing business receipts and payments, international transfers, financing, or cash management. An individual with significant assets may instead be looking for support with investments, diversification, or wealth management.
However, the exact range of services depends on each institution and, above all, on the customer's profile. It is therefore preferable not to choose a bank solely based on its general reputation. Fees, access requirements for certain services, investment options, and the level of support provided should be assessed directly with the institution.
Are Andorran banks safe?
Banking security should never be assessed solely on the basis of a country's image or a bank's commercial reputation. However, several objective factors can help provide a better understanding of the Andorran framework.
Banking activities are notably subject to the supervision of the Andorran Financial Authority, the AFA. The framework also includes other competent bodies, particularly in the areas of anti-money laundering and bank resolution. Andorran Banking states that institutions are supervised by the AFA, the UIFAND, and, within its area of responsibility, the AREB.
Andorra also has a deposit guarantee scheme. The guaranteed amount is capped at €100,000 under the conditions set out in the applicable scheme. This level of coverage is notably set out in the banking regulations published by Andorran Banking. This guarantee obviously does not mean that an investment or financial product is risk-free. A distinction must be made between a bank deposit covered by the applicable protection scheme and an investment whose value may rise or fall.
The advantages of banking in Andorra
For someone who genuinely lives or carries out business activities in the Principality, having a local bank account is primarily practical. It makes it easier to manage everyday expenses and transactions related to an economic activity established in the country.
The international nature of the sector can also appeal to people whose assets, income, or professional activities involve several countries. Private banking and asset management play an important role in the Andorran banking model, which explains why some institutions have developed an international clientele.
The relatively small size of the market can also encourage a more personalized relationship with a financial adviser, particularly for complex personal wealth or business matters. However, this depends heavily on the bank, the level of service selected, and the customer's profile.
However, caution is warranted when it comes to the idea of “banking confidentiality.” An Andorran bank naturally protects its customers' data within the applicable legal framework, but this does not mean that accounts are anonymous or invisible to foreign tax authorities.
Andorra applies the automatic exchange of financial account information in accordance with the international mechanisms to which it is a party. Presenting an Andorran bank today as a way of avoiding tax reporting obligations would therefore be misleading.
Andorran taxation and bank accounts: two issues that should not be confused
The Principality's relatively moderate tax system often contributes to its appeal, but opening a bank account in Andorra and becoming an Andorran tax resident are two different things. Simply depositing money in a bank in the country does not automatically transfer your tax residence to Andorra, nor does it exempt you from complying with the tax obligations of your country of residence.
This is particularly important for non-residents. Depending on their situation, they may have to declare the existence of accounts held abroad or income generated by certain investments. The applicable rules depend on the country of tax residence, the nature of the income, and, where applicable, the relevant tax treaties.
An international banking arrangement should therefore not be built solely around an advertised tax rate. Before relocating, restructuring your assets, or transferring significant amounts of capital, it is advisable to check the tax implications in each country concerned with a qualified professional.
Does banking secrecy still exist in Andorra?
Not in the sense traditionally associated with the term. Andorra has fundamentally transformed its tax transparency framework. The country participates in the international standard for the automatic exchange of financial account information and signed the multilateral agreement enabling this mechanism as early as 2015. In October 2025, Andorra and the European Union also signed a protocol designed to adapt their agreement to the OECD's new international tax transparency standards.
A bank is still required to protect its customers' information against improper disclosure. However, this protection of personal data should not be confused with tax anonymity. For someone wishing to open an account legally, this development is not necessarily a disadvantage. It primarily means that they must be able to clearly explain their activity, tax residence, and the origin of their assets.
What constraints should you be aware of?
The main change for people accustomed to very quick bank account openings is the level of compliance required. A bank needs to understand who its customer is, what they do, where their funds come from, and how they intend to use the account. In a straightforward case, these checks can be relatively smooth. As soon as several companies, countries, sources of income, or significant asset movements are involved, the assessment naturally becomes more thorough.
This requirement can make opening an account seem complicated, particularly for a non-resident. However, it reflects the know-your-customer and anti-money laundering and counter-terrorist financing obligations to which the financial sector is subject.
Fees are another point to check. An Andorran bank is not necessarily cheaper than a French or Spanish bank, or than an online banking provider. Account maintenance fees, cards, international transfers, currency exchange, securities transactions, and portfolio management can significantly affect the annual cost of a banking relationship. Rather than comparing only the price of an individual service, it is more prudent to request a complete fee schedule based on how you intend to use the account.
How do you open a bank account in Andorra?
The process generally begins with an assessment of the applicant's profile. The bank will seek to identify the person wishing to become a customer, their tax residence, their professional activity, and the source of the funds to be deposited.
A valid identity document and proof of address are naturally among the documents that may be requested. Depending on the situation, the bank may also ask for information about professional activity, income, company ownership, tax returns, or the origin of assets.
For an employee, providing this information may be relatively straightforward. For an entrepreneur, company director, or person whose wealth has been built through several transactions, the bank may seek to understand the economic origin of the funds in greater detail.
This is a point that is often underestimated. Providing a bank statement showing that a certain amount is already held in an account does not necessarily prove where the money came from. In some cases, you will need to explain how the funds were accumulated: professional activity, dividends, the sale of a company, a property sale, an inheritance, or another wealth-related event. The bank remains free to accept or decline a business relationship based on its assessment of the application and its risk policy.

Can you open an account in Andorra without being a resident?
It is possible, but this does not mean that a non-resident automatically has the right to open an account. The level of scrutiny generally depends on the applicant’s profile. Their nationality, country of tax residence, professional activity, source of income, intended transactions, and the complexity of their assets may all be taken into account.
It is also preferable not to rely on the universal minimum amounts sometimes advertised online. There is no single threshold that applies to every account and every bank. A high investment requirement may apply to a private banking service without necessarily corresponding to the conditions for a more conventional bank account.
A non-resident should therefore aim to present a consistent application from the outset. A bank can understand a request much more easily when the customer can explain why they want to open the account, how they intend to use it, and how the funds were accumulated.

Realize your expatriation project without further delay!
Make an appointment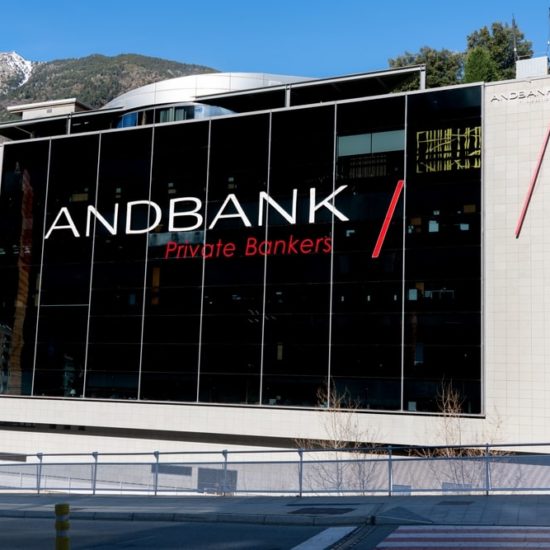
How long does it take to open an account?
There is no single timeframe that applies to every situation. The speed of the process depends in particular on the bank, the type of account requested, the quality of the documents provided, and the complexity of the applicant’s profile. An application from a salaried resident with easily identifiable income does not require the same level of compliance work as an application involving several foreign companies or different sources of wealth.
To avoid unnecessary back-and-forth, the best approach is to prepare the required supporting documents from the outset and respond precisely to requests from the compliance department. When a bank asks for an additional document, this does not necessarily mean that there is a problem with the application. A document may simply be missing to properly document a transaction or establish the origin of an asset.
How to choose between andbank, morabanc, and creand?
There is no single “best Andorran bank” in absolute terms. The right choice depends above all on what you actually want to do.
For a resident primarily looking for a current account, a card, and everyday banking services, the simplicity of the app, availability of branches, quality of customer service, and fees will probably be the main priorities.
For an entrepreneur, it will be more relevant to examine payment facilities, international transfers, business account management, financing solutions, and the bank’s ability to support business growth.
For someone looking for wealth management services, the criteria are different again. You should examine the investment philosophy, management fees, range of products offered, level of advice, any potential conflicts of interest, and the quality of reporting.
Rather than relying on a bank’s general reputation, it is often more effective to request a concrete proposal from several institutions based on the same requirements. This makes the comparison much more meaningful.
Are Andorran banks interesting for French residents?
They can be, but not simply because they are located in Andorra. For someone who genuinely becomes a resident of the Principality, establishes a company there, or develops a significant part of their business there, having a local bank account can make sense.
For a French resident with no particular connection to Andorra, the potential benefits need to be assessed more carefully. Any banking or wealth diversification strategy should be weighed against fees, French reporting obligations, applicable taxation, and compliance requirements.
The location of a bank account abroad does not remove the account holder’s tax obligations. This is precisely one of the reasons why automatic exchanges of financial information between jurisdictions now play such an important role.
Before contacting an Andorran bank
Today’s Andorran banking system is quite far removed from the image of a secret account opened in a small principality away from scrutiny. It is now a sector concentrated around three banking groups, with a strong focus on commercial banking, private banking, and asset management, within a regulatory environment that has progressively moved closer to international standards.
This evolution can actually be an advantage for clients seeking an international banking relationship within a structured framework. In return, it requires greater transparency regarding the customer’s identity, tax residence, and source of funds.
Before opening an account, the most important thing is to start with your actual situation: are you a resident or non-resident, an individual or an entrepreneur, do you simply need an everyday account, or are you looking for wealth management services? Once these questions have been clarified, comparing Andbank, MoraBanc, and Creand based on their actual terms, fees, and level of service will be far more useful than choosing a bank based solely on the historical reputation of Andorra’s financial sector.
